1099-NEC: What It Is, Who Files It and How to Meet the 2026 Rules
Form 1099-NEC is the IRS form a business uses to report what it paid an independent contractor for services. Starting with payments made in 2026, you file one for each contractor you paid $2,000 or more during the year, up from $600, according to the IRS instructions for Forms 1099-MISC and 1099-NEC.
NEC stands for nonemployee compensation. If you hire a freelance designer, a cleaner or a handyman for your business, the form tells the IRS how much you paid them. If you are the contractor, it shows up in your mailbox and goes on your tax return. Below you get the test, the exceptions, the boxes and the deadlines.
What is a 1099-NEC?
A 1099-NEC is an information return. It does not calculate tax. It reports income, so the IRS can match what you paid with what the contractor declares. The payer fills it out, sends Copy B to the contractor and files Copy A with the IRS.
The IRS lists the current revision of the form on its About Form 1099-NEC page, dated December 2026.
What changed in the 1099-NEC rules for 2026?
Three things changed, and the threshold is the one that saves you the most paperwork. The IRS FAQ on Form 1099-NEC confirms the $600 rule for payments through 2025 and the $2,000 rule for payments made after December 31, 2025.
| Rule | Payments made in 2025 | Payments made in 2026 |
|---|---|---|
| Filing threshold | $600 | $2,000, with inflation adjustments possible from 2027 |
| Tips and overtime boxes | Not on the form | New boxes 1b, 1c and 1d |
| 1099-MISC rents and other income | $600 | $2,000 |
| 1099-MISC royalties | $10 | $10 |
Suppose you paid a bookkeeper $1,500 in 2025 and $1,500 again in 2026. You owed a 1099-NEC for 2025, but not for 2026, because $1,500 is below $2,000.
Who needs to file a 1099-NEC?
You need to file if a payment passes all four parts of the IRS test. Miss one and the form is not required.
- The payee is not your employee.
- You paid for services in the course of your trade or business.
- The payee is an individual, partnership or estate, or in some cases a corporation.
- You paid that payee $2,000 or more during the year, counting parts and materials that came with the service.

If you are not sure whether a worker is a contractor or an employee, settle that first. The 1099 vs W2 guide walks through the IRS control tests, because the wrong label leads to the wrong form.
Which payments do not need a 1099-NEC?
| Payment | Why no 1099-NEC | What applies instead |
|---|---|---|
| Card or payment app payments | The payment company reports them | Form 1099-K |
| Corporations, including LLCs taxed as C or S corporations | Corporations are exempt | Nothing, except legal fees |
| Employee wages | Employees are not contractors | Form W-2 |
| Merchandise, freight, storage and phone service | Not a payment for services | Nothing |
| Personal payments, like a home repair | Not part of your business | Nothing |
| Tax-exempt organizations and governments | Exempt payees | Nothing |
Attorneys are the big exception. You send a 1099-NEC to a law firm for legal services of $2,000 or more, even when it is a corporation.
Example: a bakery with five contractors
Suppose a bakery owner paid five contractors in 2026. Only two of them get a 1099-NEC.
| Contractor | Paid in 2026 | How paid | 1099-NEC? |
|---|---|---|---|
| Freelance photographer, sole proprietor | $2,400 | Check | Yes |
| Cleaner, sole proprietor | $1,800 | Bank transfer | No, below $2,000 |
| Web designer, LLC taxed as an S corporation | $3,000 | Bank transfer | No, corporation |
| Attorney, professional corporation | $2,500 | Check | Yes, legal fees |
| Graphic designer, sole proprietor | $2,600 | Credit card | No, goes on Form 1099-K |
What is the difference between 1099-NEC, 1099-MISC and 1099-K?
Use the 1099-NEC for services, the 1099-MISC for rents, prizes and other income, and let the payment company handle the 1099-K. The deadlines differ too, so do not batch them as one task.
| Form | What it reports | Threshold | Who files | Due date |
|---|---|---|---|---|
| 1099-NEC | Services by non-employees | $2,000 | The business that paid | January 31, paper or e-file |
| 1099-MISC | Rent, prizes, awards, other income | $2,000, or $10 for royalties | The business that paid | February 28 on paper, March 31 e-filed |
| 1099-K | Card and payment app transactions | Set by the IRS for payment companies | The payment company | Sent to you by the payment company |
The 1099-K rule matters for both sides. If you pay a contractor by card or through a payment app, you do not report that payment on a 1099-NEC, so the same dollars are not counted twice. The 1099-K guide for payment app sellers explains what that form looks like when you receive one.
How do you fill out a 1099-NEC box by box?
Start with a Form W-9 from the contractor. It gives you their legal name, address and Taxpayer Identification Number (TIN), which is a Social Security number or an Employer Identification Number. Then fill the boxes below.
| Box | What goes there |
|---|---|
| 1a Nonemployee compensation | Total paid for services in the year, including parts and materials |
| 1b Cash tips | The part of box 1a that was cash tips, including tips customers charged, new for 2026 |
| 1c Treasury Tipped Occupation Code | Up to two IRS codes for the occupations where the tips were earned |
| 1d Qualified overtime | Only the extra half of time-and-a-half overtime pay included in box 1a |
| 2 Direct sales checkbox | Check it if you sold $5,000 or more of consumer products to the payee for resale outside a permanent store |
| 4 Federal income tax withheld | Backup withholding, if you had to withhold |
| 5 to 7 State information | State tax withheld, state ID and state income, optional for the IRS |
One detail trips up many owners. If the contractor charges sales tax on a service and you pay it, the IRS says to include that tax in the reportable amount.
When is the 1099-NEC due?
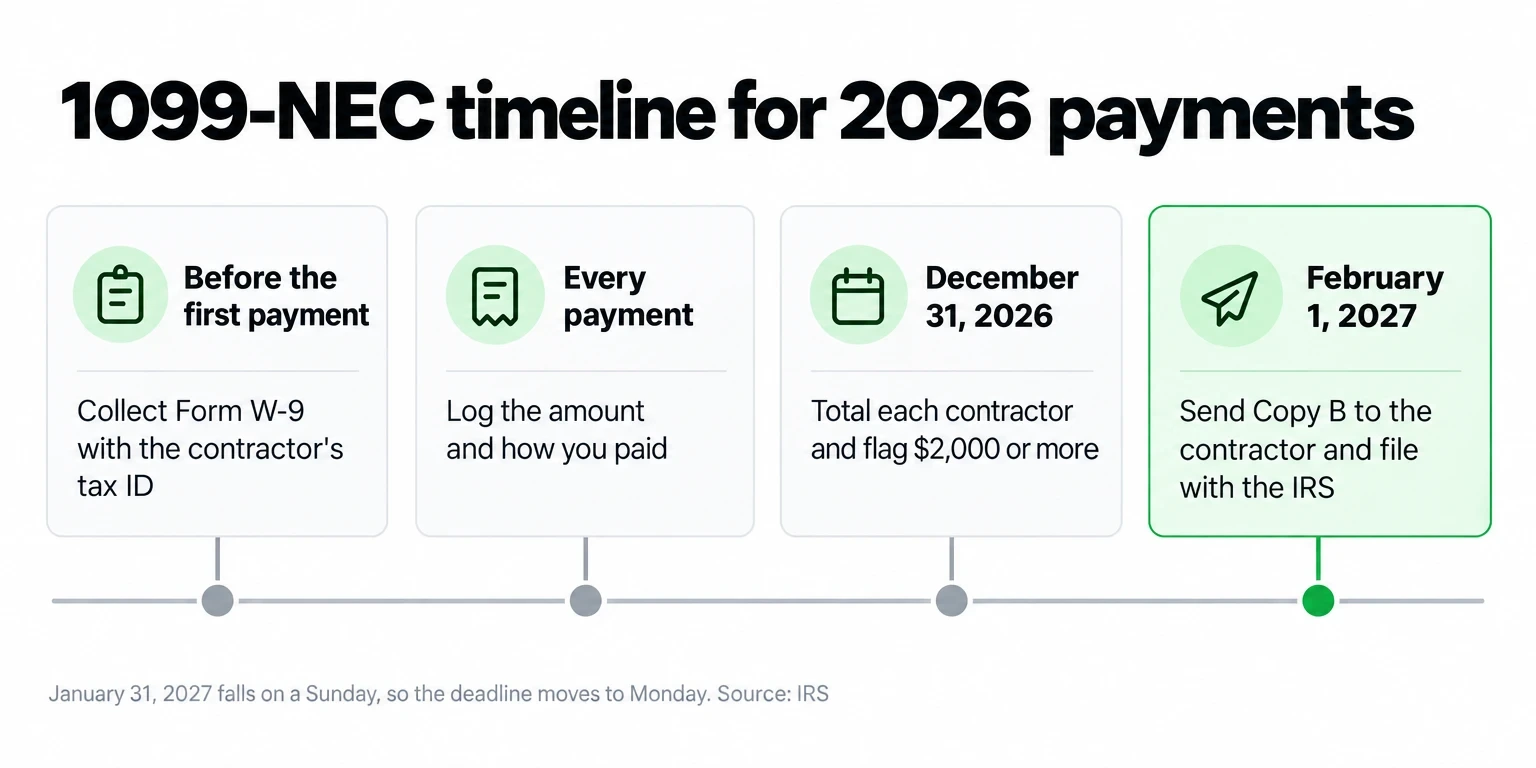
The 1099-NEC is due January 31 to both the IRS and the contractor, whether you file on paper or online. When that date lands on a weekend or holiday, you get until the next business day. For 2026 payments, January 31, 2027 is a Sunday, so your real deadline is Monday, February 1, 2027.
How do you file a 1099-NEC?
E-filing through IRIS, the free Information Returns Intake System, is the fastest route for a small business. Follow these steps.
- Collect a Form W-9 from every contractor before the first payment.
- Log each payment with the date, amount and method, so card payments stay out of your total.
- On December 31, total each contractor and flag anyone at $2,000 or more.
- File Copy A through IRIS or on paper, and send Copy B to the contractor by February 1, 2027.
- Keep a copy and the W-9 with your business records.
Two filing rules decide the method for you. If you have 10 or more information returns in total, counting all types together, you must e-file. If you file on paper, use official IRS forms for Copy A. The IRS made Copies B, 1 and 2 fillable online, but not Copy A.
What are the penalties for filing a 1099-NEC late?
Penalties apply per form and grow the longer you wait. These are the amounts the IRS lists on its information return penalties page for returns due in 2026.
| When you file | Penalty per form |
|---|---|
| Up to 30 days late | $60 |
| 31 days late through August 1 | $130 |
| After August 1, or never filed | $340 |
| Intentional disregard | $680 |
A separate penalty applies for not sending the contractor their copy. If you need more time, file Form 8809 before the deadline to ask for an extension.
What if a contractor will not give you a W-9?
Start backup withholding. When a payee fails to give you a correct TIN, the IRS requires you to hold back 24% of reportable payments and send it to the IRS, according to its backup withholding guidance. Suppose you owe a contractor $2,400 and they never return the W-9. You would withhold $576 and report it in box 4. Asking for the W-9 before the first job avoids that conversation.
What should you do if you receive a 1099-NEC?
Report the income on Schedule C and pay self-employment tax on the profit. The IRS sets the self-employment tax at 15.3%, which is 12.4% for Social Security and 2.9% for Medicare, and you owe it once your net earnings reach $400. The guide to Schedule C, line by line shows where box 1a lands.
Three habits keep you out of trouble:
- Report all your income, even from clients who never send a form.
- Compare each 1099-NEC to your invoices and ask the client to correct any wrong amount.
- Count each dollar once. If a client paid you by card, that money appears on a 1099-K, not on their 1099-NEC.
Still choosing a business structure? The comparison of LLC vs sole proprietorship covers how each option changes the forms you get.
How can JIM make tax season simpler for contractors?
Card payments do not count toward a client's $2,000 1099-NEC total, so getting paid by card leaves you with fewer forms to chase. With JIM Tap to Pay, you accept contactless cards on your phone for a flat 1.99% per sale, and the money lands in seconds on your JIM Visa Prepaid Card. For remote clients, send a Payment Link. In January, the JIM tax report puts every payment you received during the year on one Form 1099-K. Want more ways to collect from clients? See this list of freelancer payment methods.
Sell and get paid in seconds with Jim